How to Apply for Financial Aid as an Adult Learner
Applying for financial aid as an adult learner starts with the FAFSA. Call 8772187081 for guidance on grants, loans, and scholarships that fit your goals.
By Margaret Reis
Returning to school as an adult often feels like standing at the base of a mountain you have already climbed once, except this time you are carrying a mortgage, a job schedule, and maybe a family. The biggest question is rarely whether you can handle the coursework. It is whether you can afford it. The good news is that the financial aid system does not shut its doors when you turn 24. In many ways, adult learners are actually better positioned for aid than traditional students, because independence is an advantage, not a barrier. This guide walks through exactly how to apply for financial aid as an adult learner, from the moment you decide to enroll to the day the funds hit your student account.
Start With the FAFSA, Even If You Think You Earn Too Much
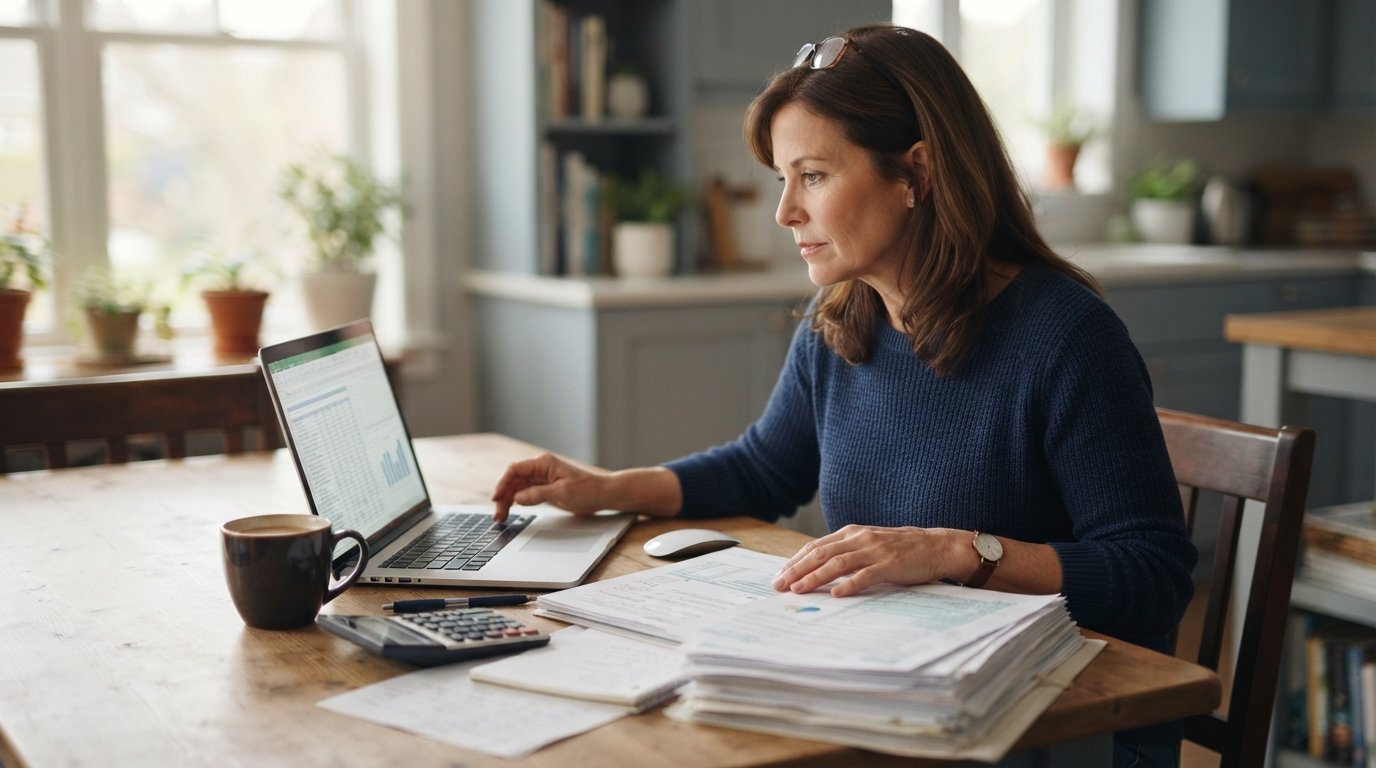
The Free Application for Federal Student Aid, commonly called the FAFSA, is the single most important form you will complete. It unlocks federal grants, work-study, and federal student loans. Many adult learners skip it because they assume their income disqualifies them. That assumption costs them money. The FAFSA is not a needs test that only rewards poverty. It is a formula that considers income, household size, number of dependents in college, and assets. A mid-career professional with two children in school may qualify for more than they expect.
Before you begin, create your Federal Student Aid ID at studentaid.gov. If you are married, your spouse may need one too. Gather your most recent tax return, W-2s, bank statements, and investment records. The form takes about 30 to 45 minutes if you have documents ready. You will list your income, your household size, and the schools you want to receive your information. There is no fee to file, and you can correct errors later.
One critical difference for adult learners is dependency status. If you are 24 or older, married, a veteran, a graduate student, or have legal dependents, you are considered independent. That means you do not report your parents' income. For many returning students, this is a major advantage because it removes an entire layer of financial documentation and often increases eligibility for need-based aid.
Deadlines matter, but they are not the same everywhere. Federal aid has a hard deadline at the end of the academic year, but state and school deadlines are often much earlier. Some states distribute limited grant funds on a first-come, first-served basis. File as soon as the FAFSA opens for your target academic year. If you are exploring programs before committing, you can still file and add schools later. In our guide on questions to ask about financial aid types, we explain how to compare offers before you commit.
Understand the Types of Aid Available to Adult Learners
Financial aid is not a single bucket. It is a collection of grants, loans, work-study, scholarships, and tax benefits. Each has different rules, repayment terms, and eligibility requirements. Understanding the categories helps you build a strategy instead of accepting the first offer that arrives.
Grants are the most desirable because they do not need to be repaid. The Pell Grant is the largest federal grant program for undergraduates, and adult learners are eligible if they meet income and enrollment criteria. State grants vary widely. Some states have dedicated programs for returning adults, displaced workers, or specific fields like nursing and teaching. Institutional grants come directly from the school and may be need-based or merit-based.
Federal student loans are available to almost all students regardless of income, but they come in two main flavors: subsidized and unsubsidized. Subsidized loans are need-based, and the government pays the interest while you are in school. Unsubsidized loans accrue interest immediately. Both have fixed interest rates and income-driven repayment options. For adult learners, federal loans are often safer than private loans because of borrower protections like deferment, forbearance, and forgiveness programs.
Work-study is a part-time job program funded by the federal government. It is not always practical for adults with full-time careers, but some schools offer work-study positions in research, administration, or community service that can fit around evening and weekend classes. Scholarships are another avenue. Many are targeted specifically at adult learners, veterans, single parents, and career changers. Do not assume scholarships are only for teenagers. Search databases, ask your employer, and check professional associations in your field.
- Federal Pell Grants: need-based, no repayment, available to undergraduates.
- State and institutional grants: vary by location and school, often have early deadlines.
- Federal student loans: fixed rates, income-driven repayment, deferment options.
- Work-study: part-time campus jobs, limited availability, flexible scheduling.
- Scholarships: private, employer, and association awards, often overlooked by adults.
Tax benefits are the final piece. The American Opportunity Tax Credit and the Lifetime Learning Credit can reduce your tax bill by hundreds or thousands of dollars. You claim them when you file your taxes, not on the FAFSA. Keep your tuition statements and receipts. These credits are not advertised as financial aid, but they function like a reimbursement for qualified education expenses.
Apply for Scholarships and Employer Benefits
The FAFSA is the foundation, but it is not the ceiling. Adult learners have access to a range of funding sources that traditional students often do not. Your employer may offer tuition reimbursement, tuition assistance, or direct billing arrangements with local colleges. Ask your human resources department whether your company has a formal education benefit. Some employers pay upfront, while others reimburse after you earn a passing grade. Either way, it reduces your out-of-pocket cost.
Professional associations, unions, and community organizations frequently offer scholarships for returning students. The application process is often simpler than federal aid, and the competition is smaller because many adults never apply. Search for scholarships tied to your industry, your demographic, or your career goal. For example, a nursing association may offer awards for current healthcare workers pursuing a BSN. A technology council may fund certifications for career changers.
Do not ignore small awards. A $500 scholarship pays for books or a portion of tuition. Five small scholarships can add up to real money. Keep a spreadsheet of deadlines, requirements, and submission status. Reuse essays where possible, but tailor them to each prompt. If you are comparing programs and want to explore options before applying, a college matching site like TopStudents can help you browse online and on-campus degree programs and request information without obligation.
Another often-missed option is the tuition installment plan. Many schools let you split your bill into monthly payments instead of paying a lump sum at the start of the term. This is not financial aid in the traditional sense, but it is a cash-flow tool that makes adult education more manageable. Combine it with employer benefits and a small scholarship, and your out-of-pocket cost can drop dramatically.
Complete Institutional Aid Applications and Verify Your Status
Many colleges require their own financial aid forms in addition to the FAFSA. The CSS Profile is used by some private schools to award institutional aid. Others have a simple institutional application or a scholarship essay. Check each school's financial aid website for specific requirements. Missing one form can delay your entire package.
After you submit the FAFSA, you will receive a Student Aid Index, which replaced the Expected Family Contribution. This number helps schools determine your need. You will also receive an aid offer from each school that admits you. The offer lists grants, loans, and work-study. Read it carefully. Compare the net cost, which is the total cost of attendance minus grants and scholarships. Loans are not free money, so do not treat them as equivalent to grants.
If your financial situation changes after you file, such as a job loss, divorce, or medical emergency, contact the financial aid office. Most schools have a professional judgment process that allows them to adjust your aid based on new circumstances. Adult learners often experience income changes mid-year, so this option is worth exploring. You may need to provide documentation, but it can lead to a better package.
Verification is another step that trips up adult learners. The Department of Education randomly selects a portion of FAFSAs for verification, which means you must submit additional documents like tax transcripts or proof of household size. Respond quickly. If you ignore the request, your aid will not disburse. Keep copies of everything you send.
Manage Loans Wisely and Plan for Repayment
Borrowing as an adult is different from borrowing at 18. You likely have existing financial obligations, a credit history, and a clearer sense of what your degree is worth. That awareness is an advantage. Take only what you need. Just because you are offered a loan does not mean you must accept the full amount. You can decline a portion of it or return unused funds within a certain window.
Federal loans come with repayment plans tied to income. If you are working full-time while studying, you may not need to make payments until you graduate or drop below half-time enrollment. After you leave school, you can choose a standard 10-year plan, a graduated plan, or an income-driven plan. Income-driven repayment caps your monthly payment at a percentage of your discretionary income and forgives the remaining balance after 20 or 25 years. Public Service Loan Forgiveness is another option if you work for a qualifying employer.
Private loans should be a last resort. They often have variable interest rates, fewer borrower protections, and no income-driven repayment. If you must borrow privately, compare offers from multiple lenders and consider bringing a co-signer to lower the rate. But for most adult learners, federal loans are the better choice because of their flexibility.
Keep track of your loan servicer. You will have a different servicer for federal loans than for private loans. Set up an online account, enable paperless statements, and mark repayment dates on your calendar. If you are still in school, you can make interest-only payments on unsubsidized loans to reduce capitalization. Small payments now can save thousands later.
Build a Timeline That Works for Your Life
Applying for financial aid as an adult learner is not a one-day task. It is a sequence that starts months before your first class. A realistic timeline reduces stress and prevents missed deadlines. Here is a framework you can adapt to your schedule.
- Six to twelve months before enrollment: Research programs, request information, and ask about financial aid options.
- Three to six months before: File the FAFSA, apply for scholarships, and check employer benefits.
- Two to three months before: Submit institutional aid forms, compare offers, and complete verification if selected.
- One month before: Accept or decline aid, set up payment plans, and confirm disbursement dates.
- After classes start: Keep receipts for tax credits, monitor your student account, and adjust your budget as needed.
This timeline is flexible. Some adult learners decide in June to start in August. In that case, move quickly and prioritize the FAFSA and any state grants with rolling deadlines. Other adults plan a year in advance, which gives them time to save and apply for more scholarships. Either way, the key is to treat financial aid as a process, not a single form.
Communication is your best tool. Introduce yourself to the financial aid office at your school. Ask questions. Tell them you are an adult learner with specific circumstances. They can point you toward grants, payment plans, and scholarships you might not find on your own. You are not bothering them. You are using the resources your tuition helps fund.
Finally, remember that financial aid is not a sign of weakness. It is a tool. Adult learners bring experience, focus, and real-world context to the classroom. The aid system exists to make that return possible. Use it strategically, borrow only what you need, and keep your eye on the goal: a credential that advances your career and your life.